I keep getting credit card upgrade offers. Here’s when I take them


 Reading Time: 4 min
I pay close to $2,500 every year in credit card annual fees, but I put a lot of work into determining which cards are worth it and which ones aren’t. One thing that makes this especially challenging is when I get offers to upgrade my existing cards to cards with more benefits and higher annual fees.
If you have decent credit and a long-term relationship with a credit card issuer, odds are that you’ll get offers to upgrade your current cards. Here’s how to know whether you should accept those offers, and when it’s better to apply for a new card outright.
Are you double-dipping on your online purchases?
FROM OUR PARTNER AT TOPCASHBACK Points Path Insiders know that earning points and miles with credit cards is only half the journey. To truly maximize your return, you need to stack them. TopCashback is the ultimate multiplier, giving you up to 15% back on the brands you already shop — from major retailers to booking sites. Because TopCashback passes 100% of its commissions directly to you, it consistently beats other portals on payout rates. Stack your cash back and cash out with zero minimum payout limits.
Stack your cash backWhen to reject an upgrade offer
More often than not, if you upgrade your credit card, you’ll become ineligible to ever receive a welcome bonus on that card. If this is the case and the welcome bonus on your desired card is high, it doesn’t make sense to accept the upgrade offer and forfeit lucrative rewards.
Even if you receive an upgrade offer that allows you to earn points and miles, compare that offer with whatever the current welcome bonus is on that card. For instance, I recently received an email from American Express letting me know I was eligible for 50,000 bonus SkyMiles if I upgraded my Delta SkyMiles® Gold American Express Card to the Delta SkyMiles® Platinum American Express Card and spent $3,000 within the first six months of the upgrade.
However, at that time the Delta SkyMiles Platinum Card was offering new cardholders a welcome bonus of up to 90,000 SkyMiles with the same spending requirement as my upgrade offer. (Note that this same offer isn’t available as of publish time.) 40,000 SkyMiles is a big difference. I didn’t accept that offer, and then American Express sent me a new offer to upgrade to the Delta SkyMiles Reserve® American Express Card and earn 60,000 bonus miles. Again, there’s a 40,000-mile difference between this upgrade offer and the welcome offer that was available to new cardholders at that moment.
When to upgrade your credit card
As I said, I receive upgrade offers all the time. I don’t normally accept them, but there are a few situations where upgrading a credit card can actually make sense.
If you are ineligible for a welcome offer for whatever reason, you might still be eligible for an upgrade offer. For instance, I was a cardholder of the Delta SkyMiles Gold Card, and I accepted an upgrade offer to the Delta SkyMiles Platinum Card in 2021. I then downgraded that card back to the SkyMiles Gold card a few years later when the annual fee increased.
According to the SkyMiles Platinum card’s terms and conditions, I would be ineligible for a welcome offer because I previously had that card. However, that line isn’t in the terms and conditions of the upgrade offer. If I wanted the SkyMiles Platinum, I could upgrade to earn bonus miles.
Other scenarios where it could make sense to upgrade your card include:
- If you’re upgrading a starter credit card that doesn’t offer a rewards program
- If you want to avoid a hard pull on your credit report
- If you’re ineligible to get approved for a card but you really want to take advantage of its benefits.
For instance, if you really need the Chase Sapphire Reserve but you won’t get approved due to Chase’s 5/24 rule, you can upgrade your Chase Sapphire Preferred as a last resort.
In case you missed it...
How AI cut a $1,310 hotel stay to $460The difference between card upgrades and product changes
An important caveat is that some issuers use the term “upgrade” to refer to any product change, even if you’re technically downgrading your credit card.
For instance, a few years ago, I “upgraded” my Capital One Venture Rewards Card (with a $95 annual fee) to the Capital One VentureOne (with a $0 annual fee and fewer benefits).
I did this because I’d been approved for the more premium Capital One Venture X and didn’t want to pay the annual fee on my Venture Rewards Card to receive essentially a pared-down version of perks that I got with my new Venture X, but I also didn’t want to close my account and give up my available credit.
This is a great strategy if you want a cash-back card with solid earning potential but a lackluster welcome bonus. Apply for a card with a better bonus, then “upgrade” it to a no-annual-fee version after a year while keeping the credit line.
The most packable Kindle yet now comes in aluminum
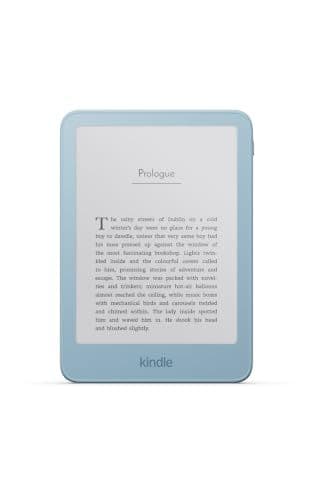
Amazon just redesigned the entire Kindle lineup. The 6-inch Kindle has a flush-front screen, a matte aluminum back, and up to 6 weeks of battery, so it slips into a pocket and outlasts most trips.
Get it at Amazon