I ran the math on my Sapphire Reserve’s $75,000 spending perks


 Reading Time: 4 min
My Chase Sapphire Reserve dangles elite status with three travel brands and $750 in credits in front of me every year, but only if I put $75,000 on the card. And it’s far from the only card to offer extra perks in exchange for meeting a high spending threshold each year.
Here’s when it makes sense to concentrate spending on one card to unlock extra benefits — and when the benefit isn’t worth the loss in rewards.
Get the Samsung Galaxy A37 5G FREE at Metro by T-Mobile!
FROM OUR PARTNER AT T MOBILE Just bring your number and sign up for our $40 Period plan. Valued at over $450 with no trade-ins or activation fees. *Just bring your number. Not available if with Metro or T-Mobile in the past 180 days. Unlimited data if using >35GB/mo; may notice reduced speeds due to prioritization.
Switch nowExamples of earned cardholder benefits
Here are just a few examples of credit cards that offer additional benefits from cardholder spending.
Hotel cards:
- Marriott Bonvoy® Bevy American Express Card: Earn a free night award worth up to 50,000 points after spending $15,000 in a calendar year.
- World of Hyatt Credit Card: Earn a second Category 1–4 free night certificate after spending $15,000 in a calendar year.
- Hilton Honors American Express Aspire Card: Earn a second free night reward when you spend $30,000 in a calendar year and a third when you reach $60,000 in a calendar year.
- Hilton Honors American Express Surpass® Card: Earn a free night reward after $15,000 spent in a calendar year.
- IHG One Rewards Premier Credit Card: Earn 15,000 bonus points, an additional 5 Elite Night Credits, and Platinum Elite status through December 31st of the following year after spending $15,000 in a calendar year.
Airline cards:
- Atmos™ Rewards Summit Visa Infinite® Credit Card: Earn a 100,000-point Global Companion Award after $60,000 spent in a cardmember year.
- Atmos™ Rewards Ascent Visa Signature®: Get a $99 Companion Fare (plus taxes and fees) each account anniversary after you spend $6,000 or more on purchases within the prior anniversary year.
- British Airways Visa Signature® Credit Card: Earn a Travel Together Ticket every calendar year you spend $30,000.
- Delta SkyMiles® Reserve American Express Card: Get unlimited Delta Sky Club access after $75,000 spent in a calendar year.
General travel rewards cards:
- The Platinum Card from American Express: Complimentary Centurion Lounge access for up to two guests when you spend $75,000 in a year.
- Chase Sapphire Reserve Credit Card: Spend $75,000 to unlock World of Hyatt Explorist status, IHG Diamond status, Southwest A-List status, a $500 Southwest Chase Travel credit, and a $250 credit for The Shops at Chase.
When does it make sense?
I have the Chase Sapphire Reserve. It unlocks more perks than any other card above, but it also has one of the highest spending requirements, so let’s break down whether it’s worth it.
To spend $75,000 on my credit card in a calendar year, I’d need to average at least $6,250 a month on my card. For many people, this likely isn’t feasible. You aren’t paying your rent or mortgage with your Sapphire Reserve, so you’d need $6,000+ in additional expenses you can actually put on a credit card each month.
Even if you did spend that much, would it be worth it? Let’s break down the perks that you’d unlock.
- World of Hyatt Explorist status: Get 20% bonus points on stays, an upgraded room (excluding suites and rooms with club lounge access), and 2:00 p.m. late checkout.
- IHG One Rewards Diamond Elite status: 100% bonus points, Hertz President’s Circle, dedicated Diamond support, and free breakfast as an option for a welcome amenity.
- $250 Credit for The Shops at Chase: A $250 credit is always nice, but I’ve honestly never used The Shops at Chase, and I already have too many credits to maximize each month.
- $500 Southwest Airlines Chase Travel credit: This is probably the most valuable benefit, but only if you fly Southwest and you don’t mind booking through the portal. I’m a full-time digital nomad and rarely fly with Southwest, so this wouldn’t be super useful.
- Southwest Airlines A-List status: Select a Preferred or Standard seat at the time of booking, Group 1 boarding, first checked bag free, 25% bonus points, and same-day standby.
In case you missed it...
Packing for multiple climates? Let AI build the listWhy I’m skipping the $75,000 tier
For me, the math just doesn’t make sense. If the majority of my $75,000 in expenses falls outside of the Sapphire Reserve’s bonus categories, I’d earn 75,000 Chase Ultimate Rewards points. Meanwhile, if I put $75,000 on my Capital One Venture X Card, I’d earn at least 150,000 Capital One Miles. I’d much rather earn extra rewards than a few elite statuses that don’t offer many concrete benefits and a couple of additional credits.
The one caveat is for hotel cards that offer a free night with $15,000 in annual spending. This can be a great deal, and it’s not incredibly challenging to spend $15,000 in a calendar year.
Still, I’d only chase one if that spending happens on its own. The same $15,000 on my Venture X would earn at least 30,000 Capital One Miles, with nothing to track.
This ultra-light travel daypack disappears into your luggage
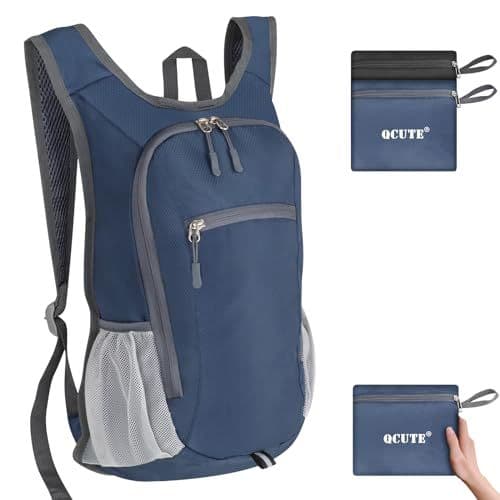
At only 0.47 pounds, this water-resistant 15L pack folds down to a tiny pouch small enough for your carry-on or pocket. It’s perfect for day outings on vacation, or for stuffing with dirty clothes on your return flight.
Get it at Amazon